The problem
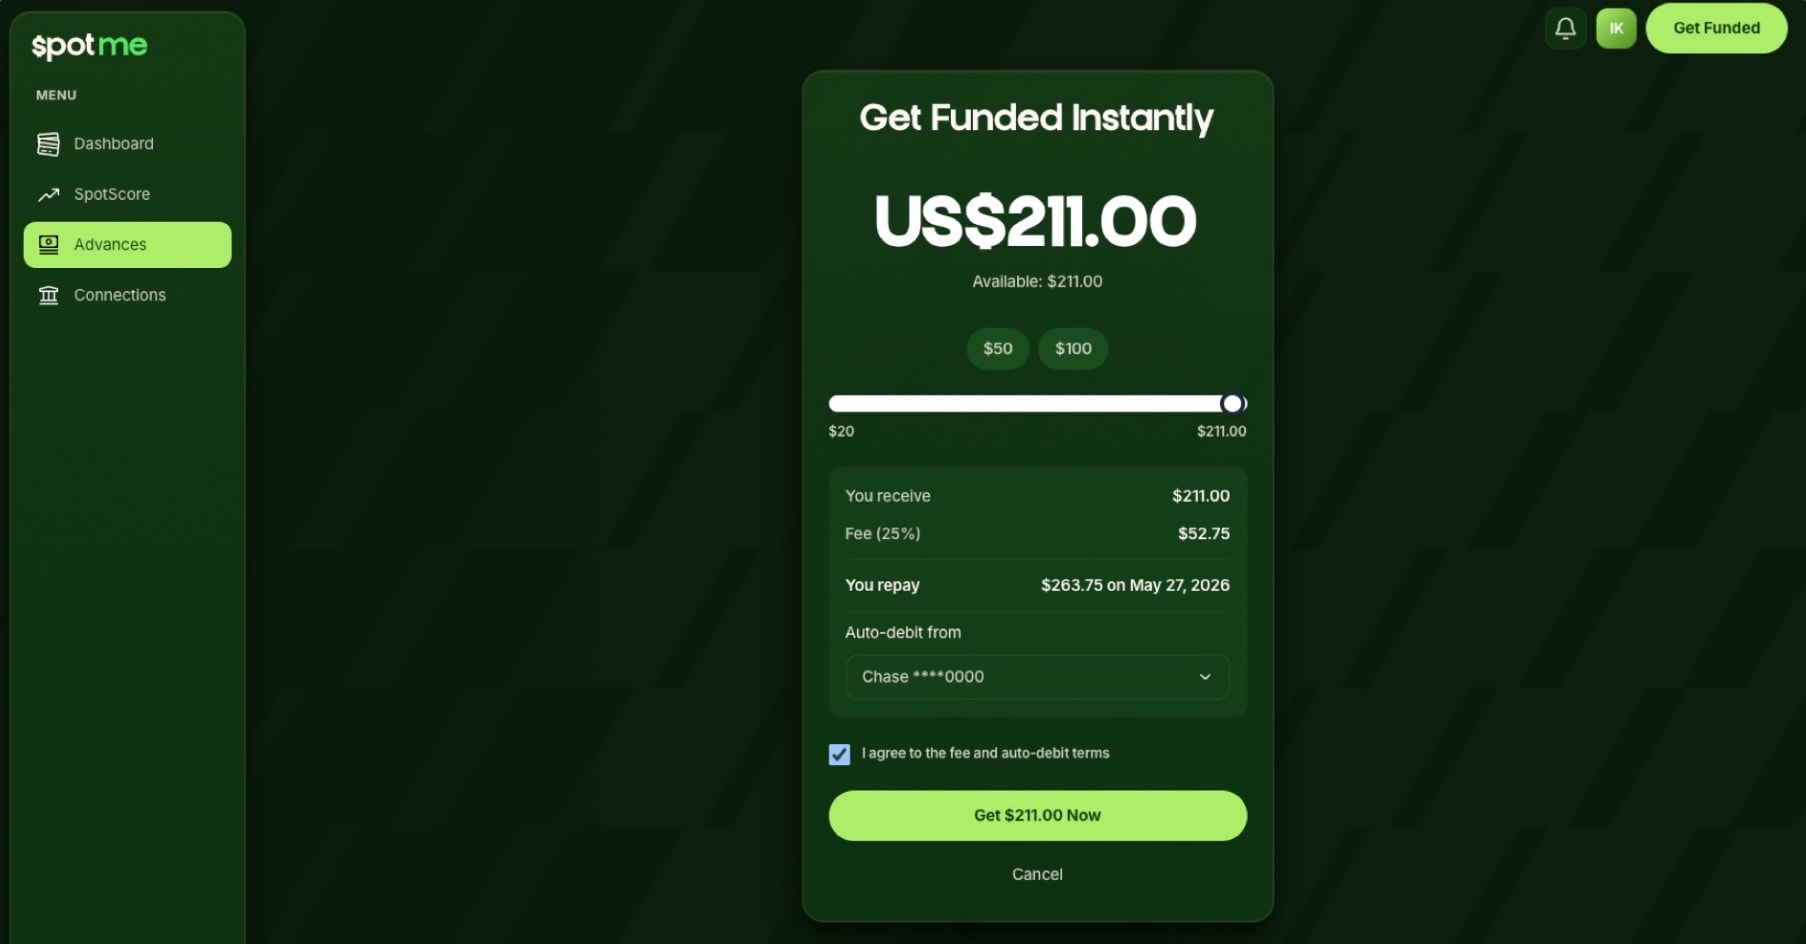
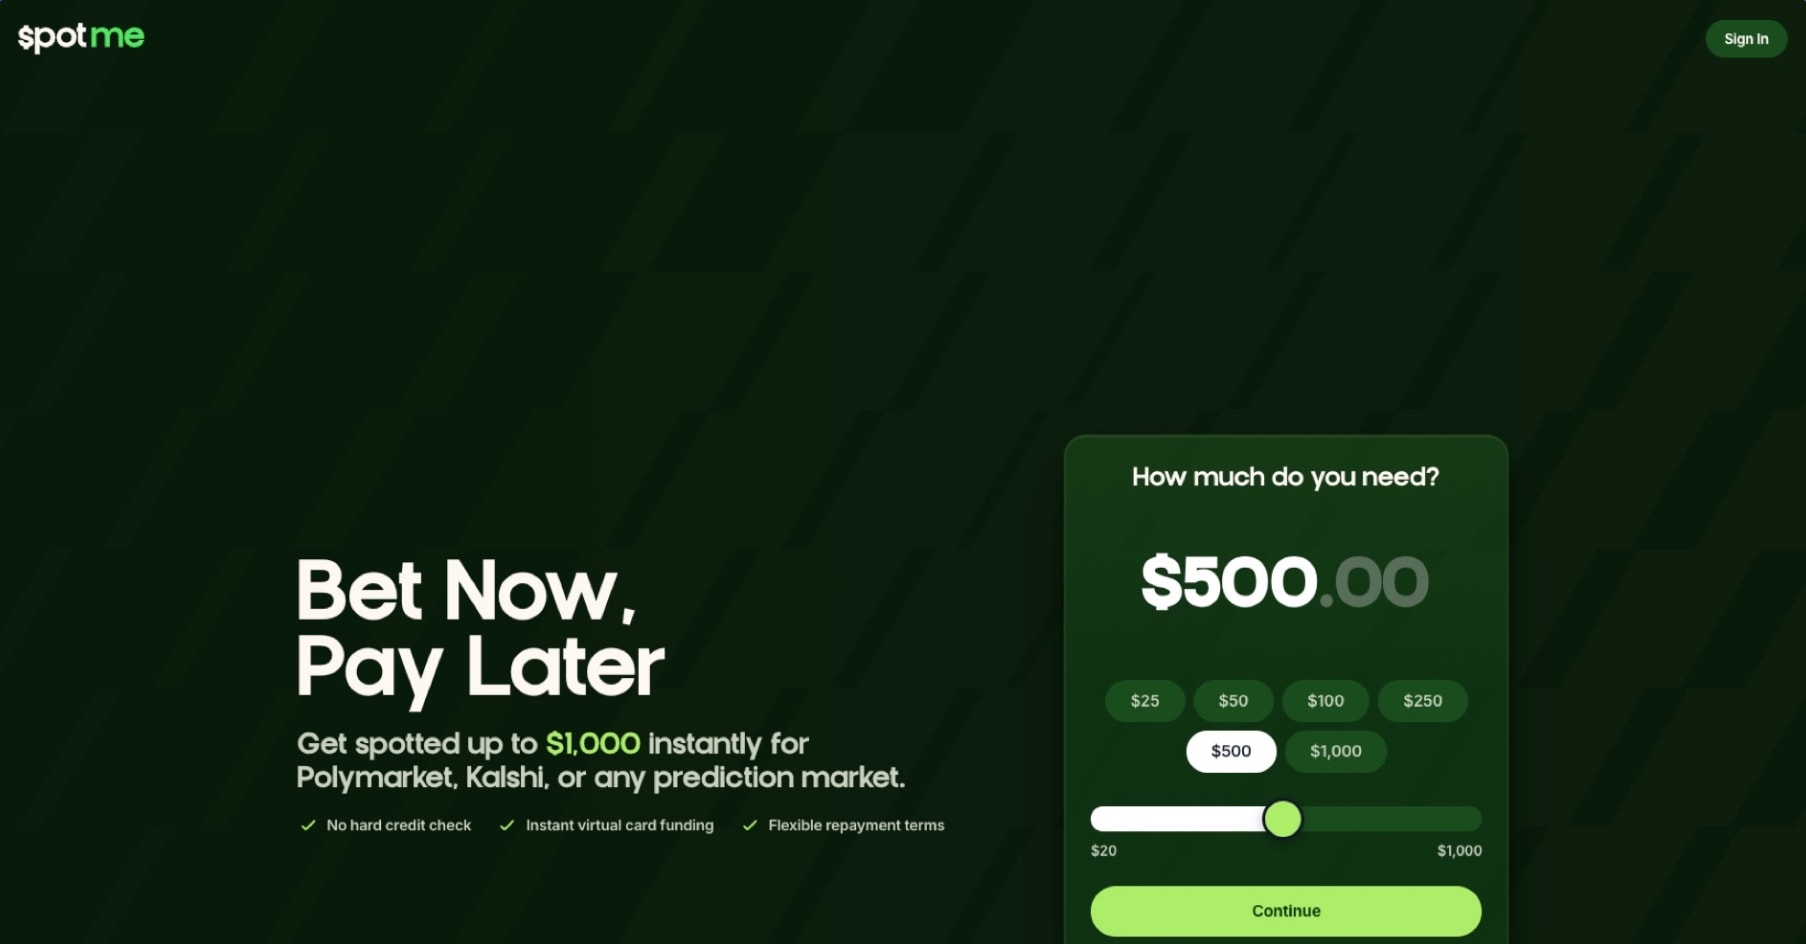
A founder had a lending product that only works if three hard things work together: decide what someone can borrow, get them the money in seconds, and get it back. Buying that off the shelf means a card programme, an underwriting vendor and a bank integration, three contracts and months before anyone can try it.
What we built
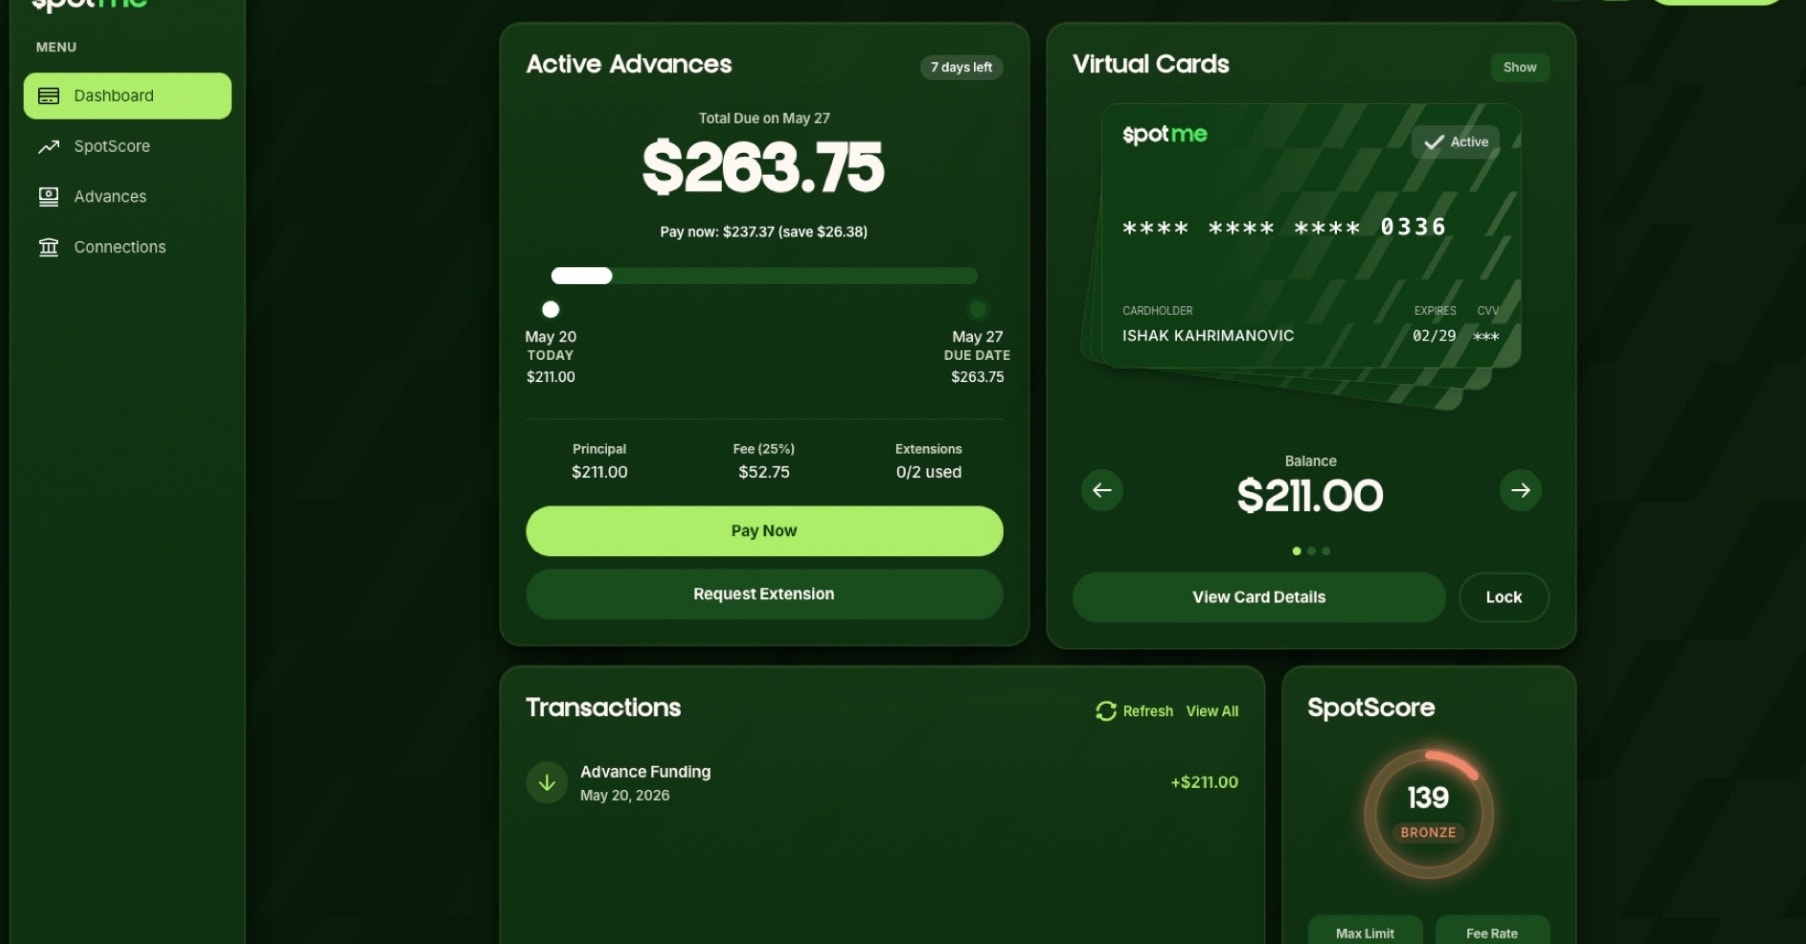
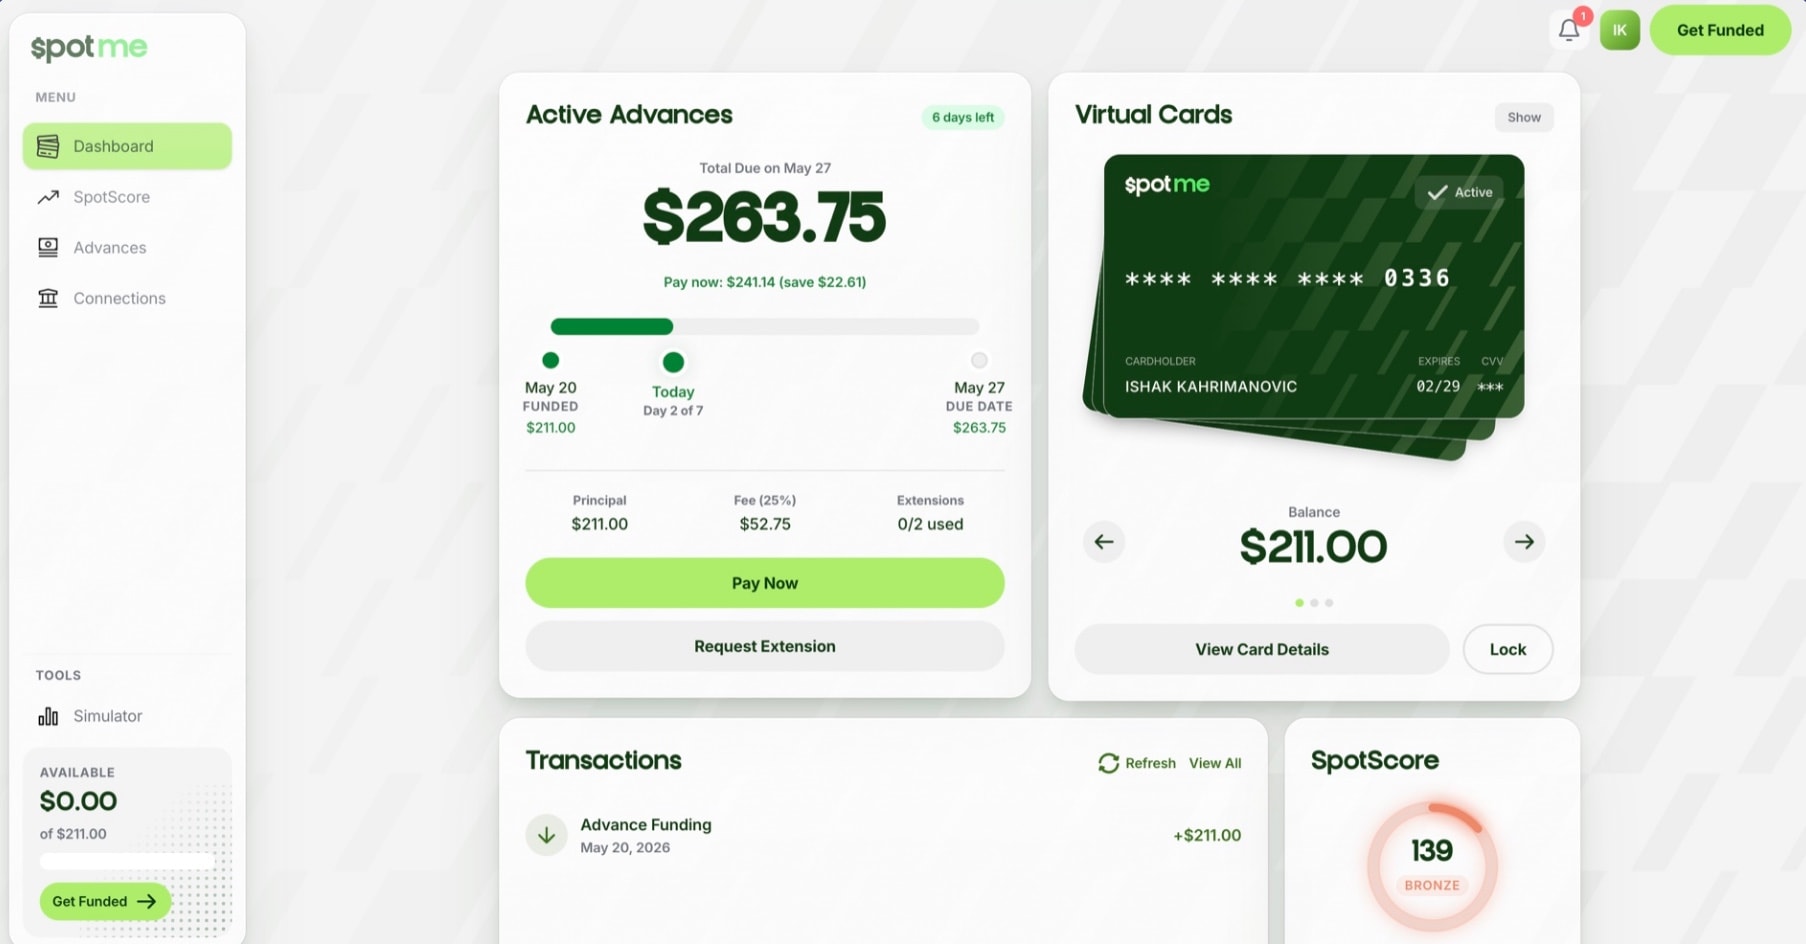
One typed backend serving native iOS, native Android and the web, so a login and a balance behave the same everywhere. Underwriting reads twelve months of bank transactions through Plaid and scores them on income stability, cash flow and repayment history, which sets a tier and a limit in dollars rather than a yes or no. Money moves on Stripe: Issuing creates the virtual card, Identity does the know-your-customer check, Payment Intents and micro-deposits verify the bank account for auto-debit. Every card authorisation is answered live by our own rules rather than left to defaults.
The result
Thirty days from nothing to a working product: a real advance, on a real card, repaid from a real bank account. The founder could put it in front of users and find out whether anyone wanted it, which is the only thing that mattered at that stage.